How Digital Farm Records Can Help Farmers Apply for Agricultural Finance
Access to finance is one of the major challenges facing farmers who want to expand production, purchase inputs, acquire machinery, improve irrigation, establish livestock enterprises or invest in processing.
For many farmers, the challenge is not only finding a lender. It is also demonstrating that the farm is a real and operating business with identifiable production activities, costs, revenues, assets and a realistic plan for repaying borrowed money.
This is where digital farm records can become useful.
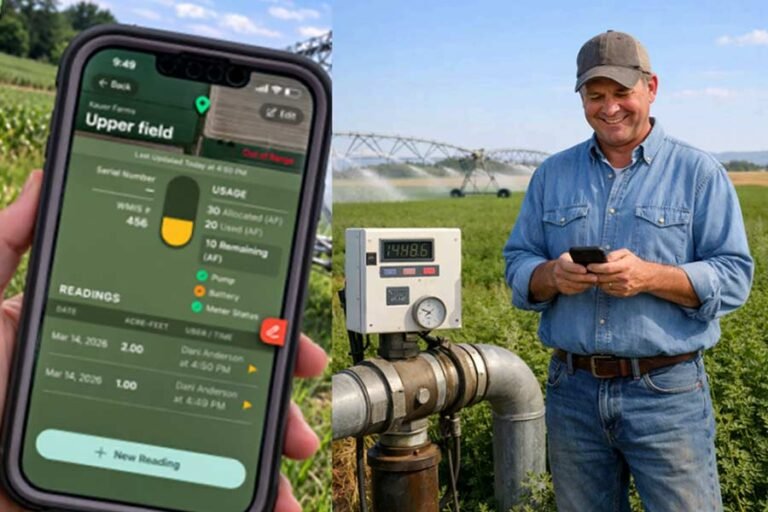
A farmer who keeps structured records of land, crops, planting activities, input purchases, labour, machinery, harvests, sales, expenses and cash flow has more information available when preparing a finance application.
Digital records do not guarantee that a farmer will receive a loan. Lenders still conduct their own credit assessment, due diligence, collateral assessment where applicable and evaluation of the proposed agricultural project.
However, organised farm records can make it easier for a farmer to present the financial and operational information required to assess the business.
A farm loan application is stronger when the farmer can demonstrate actual business activity rather than relying entirely on future projections.
For example, a crop farmer may be able to show:
| Farm information | Example of what the record can demonstrate |
|---|---|
| Land records | Area currently cultivated |
| Crop records | Crops and varieties produced |
| Planting records | Production activity and timing |
| Input records | Resources purchased and used |
| Labour records | Labour requirements and expenditure |
| Harvest records | Actual production |
| Sales records | Revenue generated |
| Expense records | Operating costs |
| Cash flow records | Timing of income and expenses |
| Asset records | Farm equipment and other productive assets |
This creates a historical picture of the farm.
A lender can then assess the information alongside other documents and its own lending criteria.
One common mistake is creating records only when a loan application is about to begin.
This can result in incomplete or reconstructed information.
Another mistake is recording expenses without dates, quantities or descriptions.
A record that simply says “fertilizer: ₦2 million” provides less information than a record showing the fertilizer type, quantity, purchase date, supplier, unit price and field where it was used.
Farmers should also avoid exaggerating production figures.
If a farmer reports yields that cannot be supported by harvest or sales records, the credibility of the entire application can be affected.
Another problem is mixing farm and household expenses.
The financial performance of the farm becomes difficult to understand when personal expenditure is recorded as a farm production cost.
Digital farm records can help farmers prepare for agricultural finance by turning farm activities into organised business information.
Production records can show what the farm produces.
Expense records can show what it costs.
Sales records can show how the farm generates revenue.
Cash-flow records can show when money enters and leaves the business.
Asset records can show productive resources.
Field records can show where production takes place.
Together, these records can help a farmer prepare a clearer production budget, financing requirement, cash-flow projection and farm business plan.
The strongest approach is to start record keeping before financing is needed.
Farmers should record production, costs, sales, assets and cash flow throughout the season instead of attempting to reconstruct the farm’s history when a loan opportunity appears.
Digital farm records cannot replace lender due diligence, collateral requirements or formal documentation. What they can do is give the farmer a more organised and evidence-based picture of the agricultural business.
For farmers seeking to expand production, improve financial management or prepare for future financing, building a reliable digital farm record system can therefore be an important part of becoming more financially organised.
Frequently Asked Questions
Can digital farm records help a farmer get an agricultural loan?
Digital farm records can help a farmer prepare and support a loan application by documenting production, expenses, sales, assets and cash flow. They do not guarantee loan approval because lenders apply their own eligibility and credit assessment requirements.
What farm records are useful when applying for agricultural finance?
Useful records can include land and field information, production history, input purchases, labour costs, machinery records, harvest quantities, sales, expenses, cash flow, assets, existing loans and supporting documents.
Can farm management software create a farm loan budget?
Many farm management systems can organise production expenses and generate financial reports that can help farmers prepare a production budget. The farmer may still need to transfer the information into a lender’s specific application or business-plan format.
Do lenders accept digital farm records?
Acceptance depends on the lender and the financing product. Some lenders may accept digital records as supporting information, while others may require specific statements, documents, physical verification or independently verifiable evidence.
Can digital farm records replace collateral?
No. Whether collateral is required depends on the lender and financing programme. Digital records document the farm’s operations and financial history, but they do not automatically substitute for required security.
How long should farmers keep digital farm records?
Farmers should retain records for multiple production seasons where possible. A longer history can provide useful information about production, costs, sales and seasonal variations. The exact retention period may also depend on tax, accounting, contractual and lender requirements.
What should a farmer record before applying for a loan?
At minimum, the farmer should maintain records of farm size, production activities, input costs, labour, machinery, harvests, sales, expenses, cash flow, assets and existing financial obligations.
Can smallholder farmers use digital records for agricultural finance?
Yes. Digital records can be useful for smallholders as well as commercial farms. The system can be simple, provided the information is accurate, consistent and relevant to the farmer’s production and financial activities.